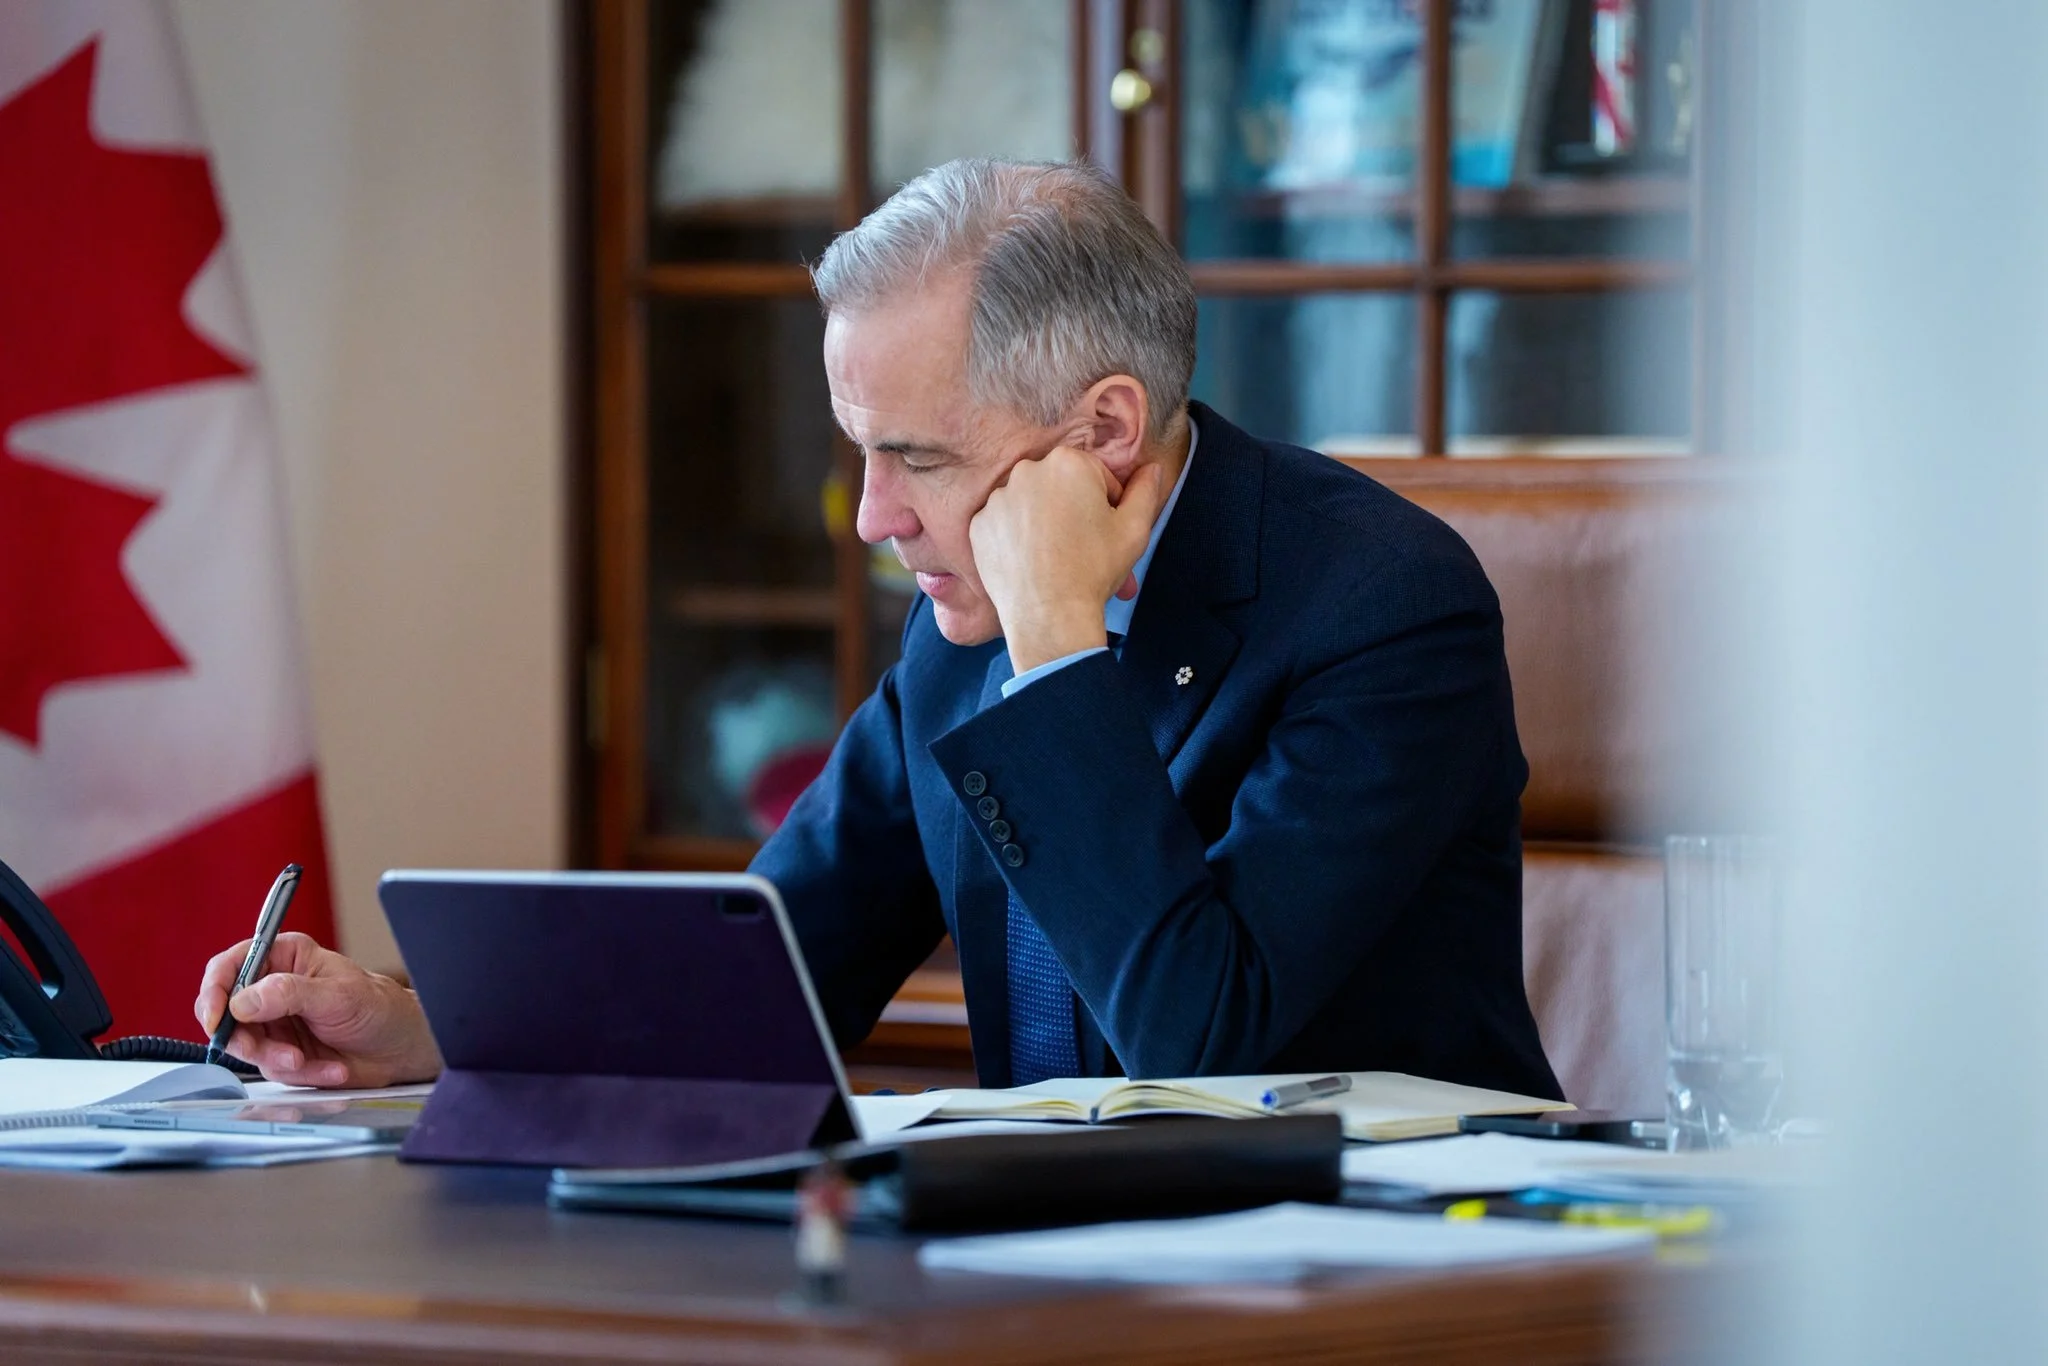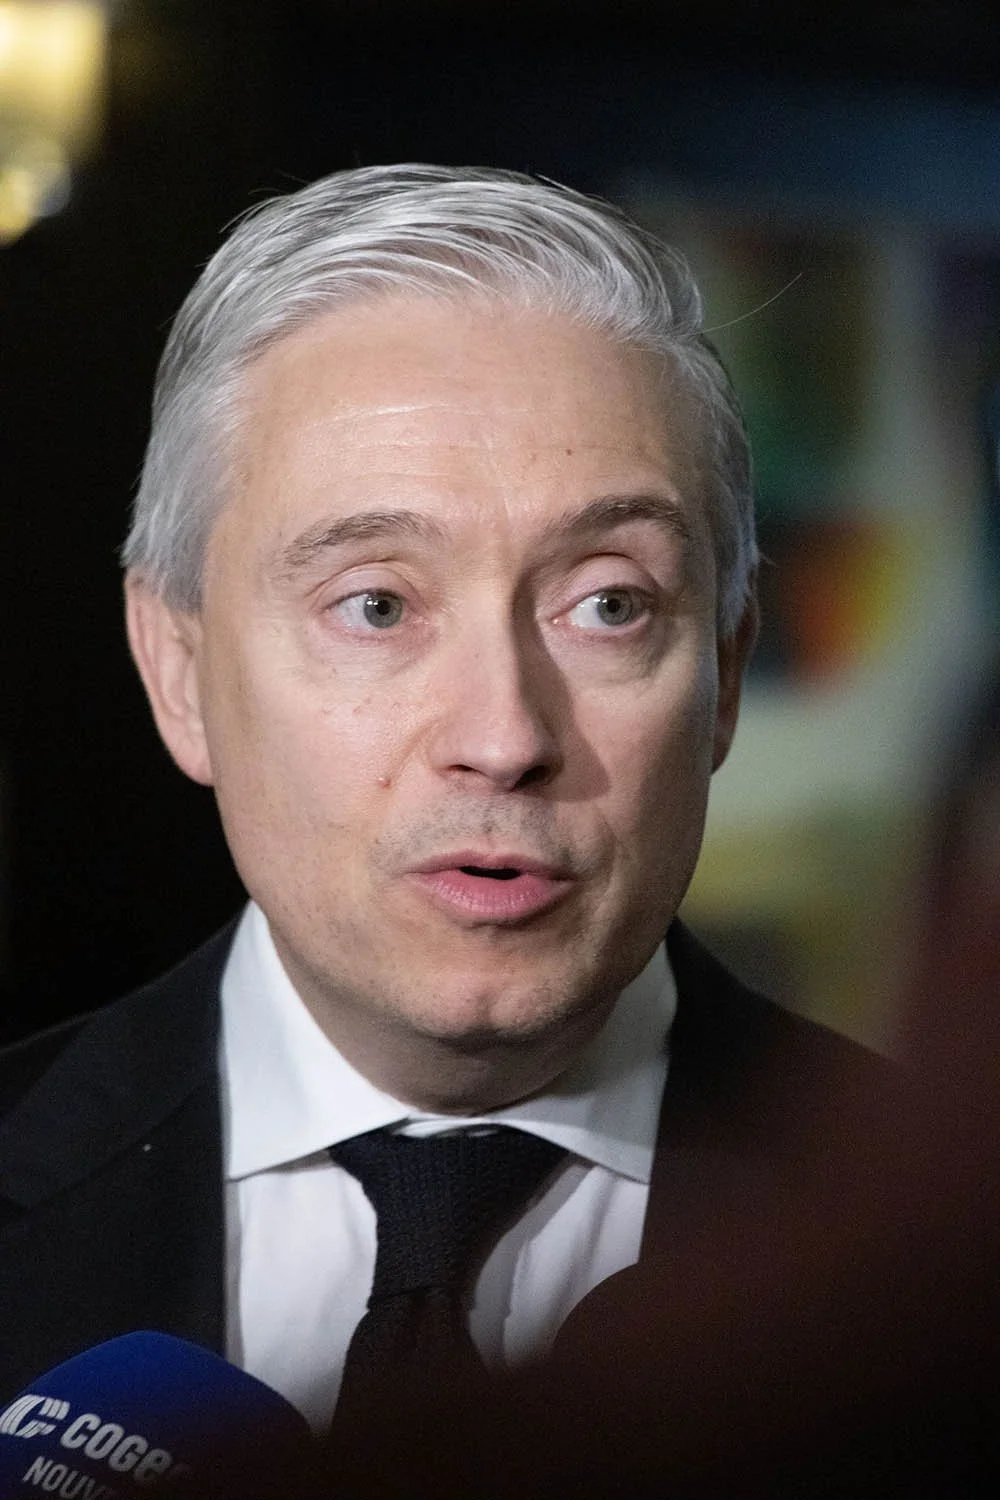
Finance Minister François-Philippe Champagne will deliver the budget on Nov. 5. / MEANS & WAYS PHOTO
Canada enters the upcoming federal budget with relatively strong fiscal fundamentals compared with its G7 peers, but rising borrowing costs, global market volatility and uncertainty over the government's investment agenda could test that advantage, says Scotiabank Vice-President Rebekah Young.
“Canada’s fiscal fundamentals remain a relative strength. Its debt and deficit metrics—federal and general government—compare favourably with those of its G7 peers, while its position as a net energy exporter offers some protection from war-related shocks,” she wrote in an analysis ahead of the Nov. 5 budget. “The Carney government heads into budget day with a solid majority, a still-strong mandate, and a two-plus year runway.”
In her report, Anticipating Canada’s 2026 Federal Budget: Ambition, Meet Arithmetic, Young writes that economic growth is expected to outpace real borrowing costs of around 1% beginning next year, helping offset debt pressures.
However, she warned that Canada's fiscal advantages could be challenged by global developments.
“Trade uncertainty, along with execution risk weigh on Canada’s relative advantage, while heavy global bond issuance and persistent inflation risk leave it exposed to broader repricing — so far more muted in Canada.”
The warnings come as Finance Minister François-Philippe Champagne prepares to table the government's second budget, with expectations of further measures to encourage private investment and economic growth.
Among the key areas to watch are federal borrowing requirements, the size of new spending commitments and whether investment incentives translate into stronger economic activity, Young said.
She estimates that roughly $110 billion in federal announcements since April could translate into approximately $63 billion in incremental fiscal costs. That figure could rise to about $80 billion on budget day, although she described the estimate as highly speculative.
Still, higher borrowing costs pose a risk.
“Debt service remains historically low as a share of revenue, but it is edging higher,” she wrote.
Scotiabank also expects non-budgetary financing requirements to increase beyond the $377 billion projected in the spring update through fiscal 2031.
“A modest deterioration in deficit ratios could therefore understate the financing costs ahead.”
Another key issue is whether Ottawa's investment strategy delivers sustained private-sector growth.
The government's $36-billion Productivity Mega Deduction, which expands immediate expensing provisions to roughly two-thirds of business investment, could lift GDP by approximately 0.3% over the longer term, according to Scotiabank.
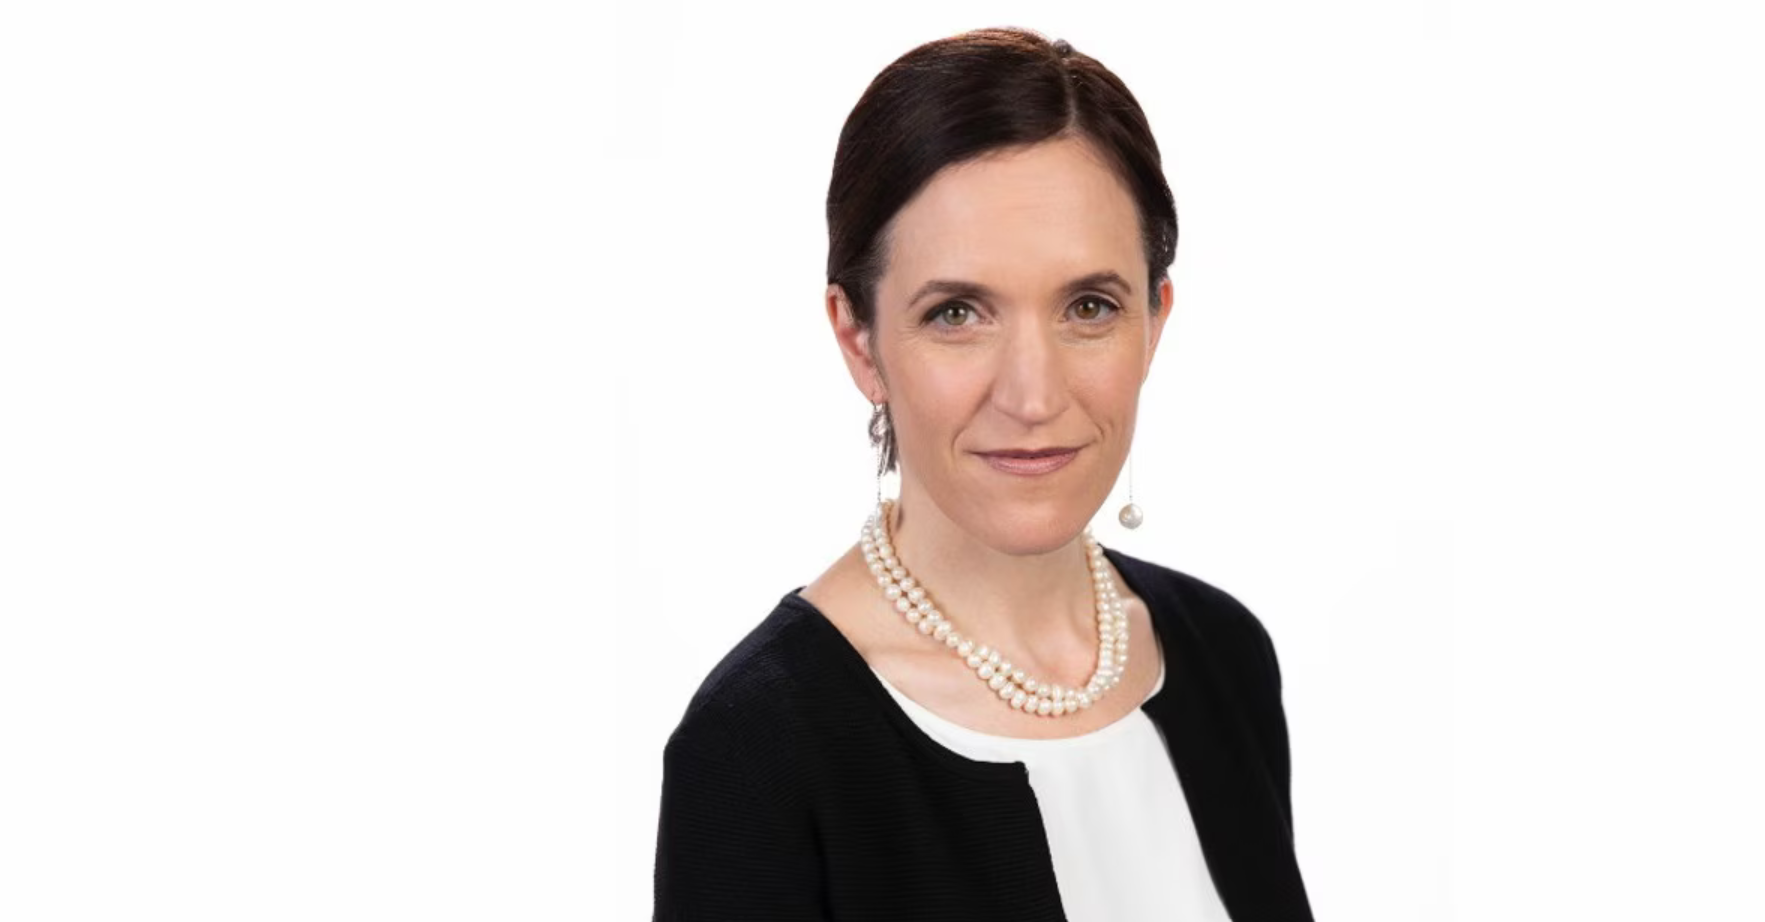
“The government has room to advance its investment agenda, but borrowing costs and global volatility raise the bar for delivery.”
— Scotiabank Vice-President Rebekah Young
But the bank cautioned that investment decisions depend on more than tax incentives.
“Demand, financing costs, regulatory timelines, labour and material constraints, and firms’ confidence will shape take-up.”
Other areas to watch include a detailed defence spending plan, further information about the proposed $25-billion Canada Strong Fund and potential changes to immigration policy aimed at addressing skilled labour shortages.
She also expects limited additional household stimulus and warned that the investment agenda could contribute to near-term inflation pressures.
Scotiabank anticipates another 75 basis points of Bank of Canada interest-rate increases over the coming quarters.
Despite those risks, Young said the government's investment-focused fiscal strategy has so far been well received.
“Global developments may overshadow the budget’s initial reception, but delivery will determine its lasting impact.”
The government's challenge will be translating its commitments into lasting economic gains, she said.
“Budget 2026 will bring ambition and arithmetic together. The government has room to advance its investment agenda, but borrowing costs and global volatility raise the bar for delivery. The ultimate measure will be whether fiscal activism produces durable gains in Canada’s productive capacity. Only time will tell.”